Meet Julie Sears: The Advisor Behind Integrity Health Insurance Advisors |
The Frisco Huddle's featured business spotlight explores how Julie Sears helps individuals, families and small businesses navigate insurance decisions. |
Featured Business: Integrity Health Insurance Advisors
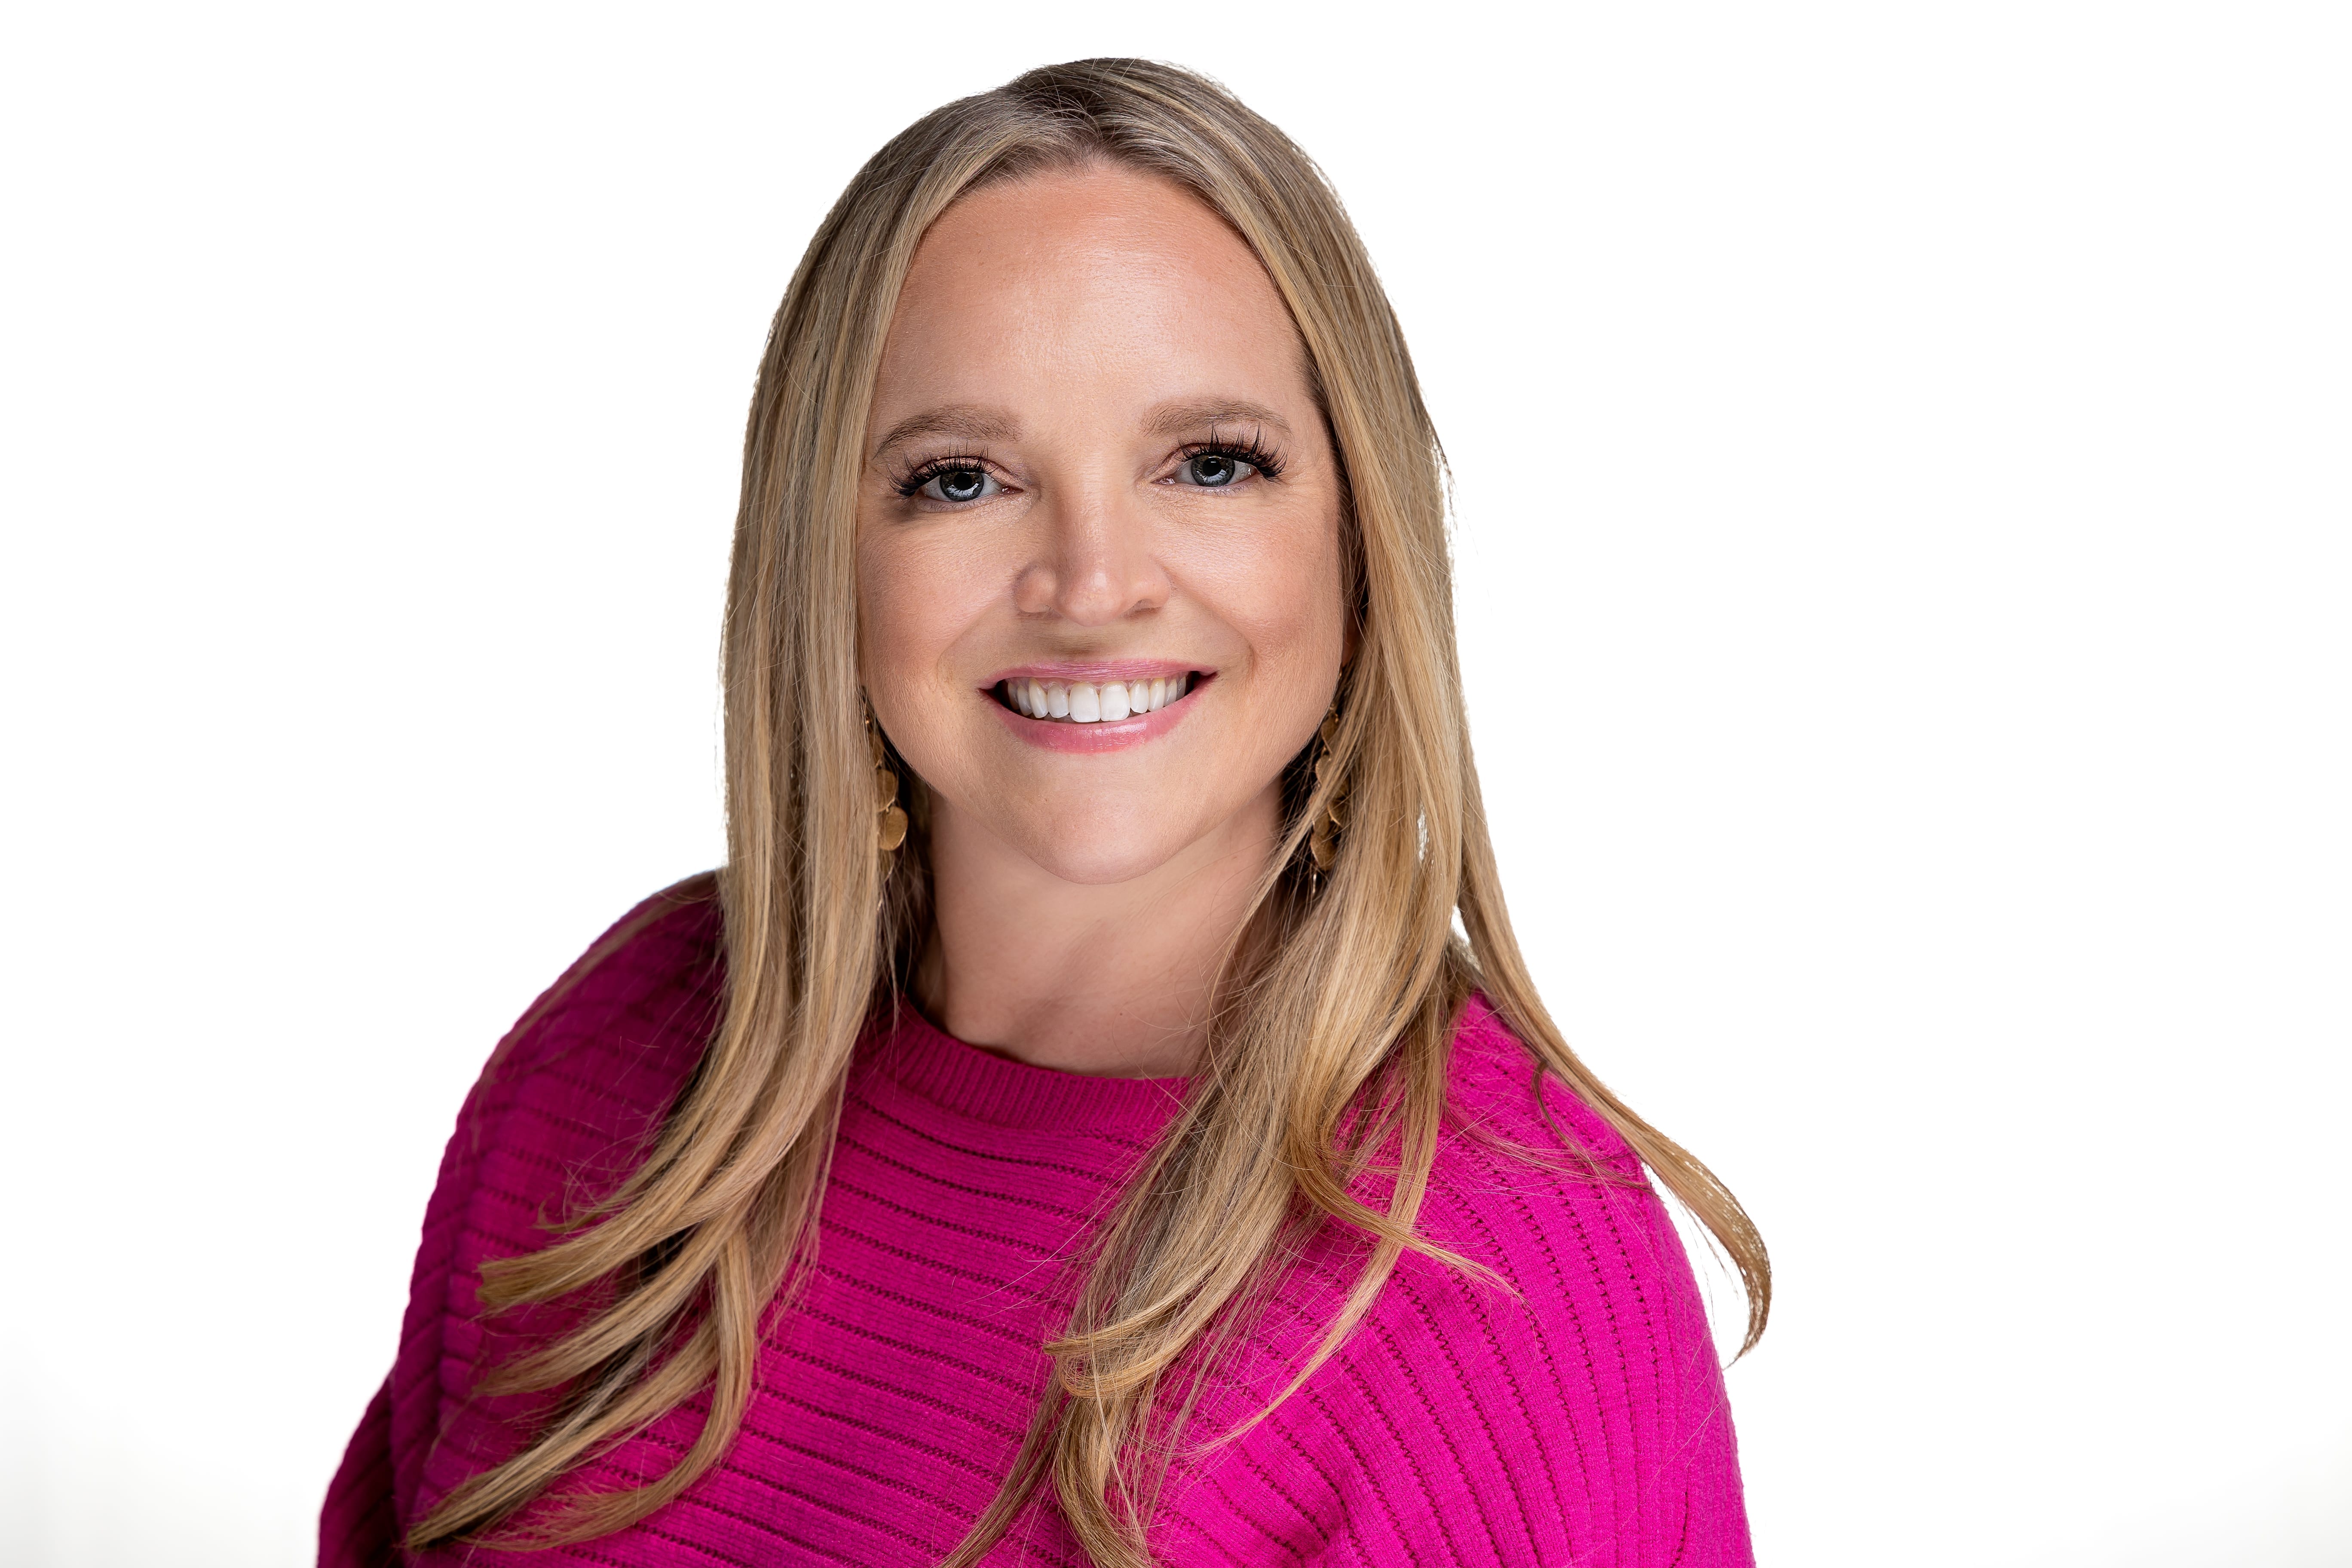
Choosing health insurance can be overwhelming, especially when families are weighing premiums, deductibles, provider networks and coverage exclusions. Julie Sears, owner and founder of Integrity Health Insurance Advisors, helps individuals, families and small-business owners make sense of their options—with straightforward answers and personalized guidance.
Featured in The Frisco Huddle’s local Health Care directory, Integrity Health Insurance Advisors provides independent guidance on private and ACA Marketplace health insurance options. Julie takes time to understand each client’s needs, budget and priorities, helping them compare coverage without pressure. There is no fee for her guidance.
Meet Founder Julie
According to her company's website, Julie began helping people with health insurance in 2017. Her earlier career included sales work supporting educators with online study resources and helping businesses identify staffing needs. Her interest in insurance grew after she encountered limited coverage choices through an employer and discovered additional private-plan options through a friend.
That experience prompted her to become a licensed insurance agent. Today, Julie says she aims to help clients compare coverage that fits their circumstances, even when the best option is not a policy her agency sells.
Coverage for Different Stages of Life
Integrity Health Insurance Advisors lists individual and family health insurance, small-business coverage, life insurance, dental insurance and vision insurance among its services. The agency also offers guidance on disability, accident and critical illness insurance.
Those products serve different purposes. Health coverage can help with eligible medical expenses, while life insurance is designed to provide financial protection to beneficiaries. Disability policies may replace a portion of income following a qualifying illness or injury, and supplemental accident or critical illness plans can provide specified benefits when policy conditions are met.
The agency says it helps customers review private and marketplace health insurance options. Actual premiums, provider networks, eligibility, exclusions and benefits vary by insurer and policy.
More Than an Enrollment Conversation
One of the agency's stated priorities is support after enrollment. Its website describes assistance with questions about billing, policy changes and coverage choices, as well as reviews of existing plans.
That review can matter because a plan that worked last year may no longer match a household's budget, medications or preferred doctors. Comparing total expected costs, not just the monthly premium, can help consumers understand their options.
How to Connect With Integrity Health Insurance Advisors
Residents interested in learning more can visit the agency's website at https://integrityhealthinsuranceadvisors.com/ or explore its local directory listing at https://thefriscohuddle.com/categories/health-care/integrity-health-insurance-advisors.
Call or text Julie at 469-348-4066. Email: [email protected].
The Frisco Huddle Business Spotlight
Our Featured Business series introduces readers to businesses listed in the local directory and the people behind them. Integrity Health Insurance Advisors is this edition's spotlight, with Julie Sears sharing her professional background and the customer-service philosophy described on her website.
Source: Integrity Health Insurance Advisors official website and The Frisco Huddle directory listing. This profile describes the business's own statements and services; it is not an independent endorsement or assessment of any insurance product. |
90 Comments
Join the conversation
I hope people remember that a no fee conversation doesn't mean every plan costs the same.
Insurance for a small business can be a lot to handle on top of everything else.
The billing help is what interests me. Picking a plan is only the beginning.
Frank O.Agreed. It's a relief to have someone to ask when a bill doesn't match what you expected.
I'd like to know how the private plans compare with Marketplace coverage.
It’s worth comparing premiums, deductibles, provider networks, benefits and exclusions side by side. The differences depend on the specific plans. Julie can help review private and Marketplace options for your circumstances.
I didn't realize supplemental accident plans have their own conditions for paying benefits.
If she's willing to say a policy she doesn't sell is better, I'd listen to her explanation.
It's worth asking about the exact hospital network too, not only individual doctors.
Brenda J.Yes, our doctor was covered once, but the hospital where she worked wasn't. I check both now.
I'd ask Julie to put the expected yearly costs side by side, not just show monthly prices.
Good reminder to look at deductibles, not just the monthly payment.
Absolutely. Looking at deductibles and other expected costs alongside the monthly premium can give you a clearer picture.
Lena OrtizExactly. A lower premium doesn't help much if the deductible is more than you can manage.
We learned the hard way to check whether our doctors are in network.
That’s an important lesson. Provider networks can vary by policy, so it’s worth checking your preferred doctors before choosing a plan.
Local help is nice when the insurance paperwork starts sounding like another language.
Life insurance and health insurance are such different decisions. Glad they explained that.
My renewal notice never makes the changes obvious, so an annual review sounds smart.
Would love to know whether she helps people compare plans when they turn 26.
The part about helping educators before insurance was an interesting bit of Julie's background.
I like the focus on budget, but keeping our pediatrician would be my first question.
Arthur S.I'd ask whether the pediatrician is in network for the specific plan, not just the insurance company.
Does Julie help small businesses with just a few employees?
Priya ShahThe article says she works with small businesses, but I'd ask whether there's a minimum number of employees.
Small-business coverage is among the agency’s listed services. Julie can tell you what options may be available for a business with just a few employees.
Having someone explain coverage exclusions would save me a lot of squinting at plan documents.
I'd still compare any recommendation with the Marketplace myself before choosing.
Nice to see the Frisco Huddle feature a service that many residents have questions about.
Disability insurance gets forgotten until someone has to miss work for months.
Dana Q.I hadn't thought much about it until a coworker was out for surgery. The waiting period seems worth checking too.
Does the free guidance cover someone who's already enrolled and just wants a review?
I appreciate seeing provider networks mentioned. A plan isn't much help if your doctor isn't covered.
Frisco families with changing medication needs should definitely check plans each year.
Sam PatelAnd check the pharmacy too. Ours wasn't preferred under the new plan.
Absolutely. Changing medication needs are one reason an annual look at coverage can be worthwhile.
I'd like to hear more about the difference between accident coverage and regular health insurance.
Regular health insurance helps pay eligible medical expenses, while supplemental accident coverage provides specified benefits when an injury meets the policy’s conditions. The details depend on the plan.
Renee B.My understanding is accident coverage pays certain benefits after a qualifying injury. I'd want the exclusions explained before adding it.
It's good the agency says it helps with billing questions after you sign up.
For me the hardest part is figuring out whether a cheaper premium means higher costs later.
Hannah C.That's my sticking point too. A lower monthly bill doesn't help much if the deductible is way higher.
Julie has been doing this since 2017, so she has seen a lot of enrollment seasons.
Luis M.I imagine the changes from year to year give her plenty to keep up with.
Critical illness coverage sounds useful, but I'd want to see what conditions actually qualify.
Erin WallaceSame. I'd also want to know if there's a waiting period before a claim can be made.
I wonder how often small businesses here revisit their coverage instead of renewing automatically.
Glad the spotlight spells out that benefits depend on the actual policy.
Monica LeeI'm glad they included that. The policy details matter more than a general list of services.
Thank you for noticing. Premiums, networks, exclusions and benefits can vary considerably from one policy to another.
I'd ask whether my specialists are in network before comparing anything else.
A yearly review makes sense. The plan that worked last year may not work now.
Tasha K.Our kids' needs changed this year, so we're looking at more than the premium this time.
Would be helpful to know if she can explain out of pocket maximums in plain English.
Ben AlvarezYes please. I'd want to know what counts toward that maximum and what doesn't.
I like that Julie's own experience with limited employer coverage led her into this work.
Julie’s experience with limited employer coverage helps explain why she emphasizes comparing options that fit each person’s circumstances.
Dental and vision are easy to overlook when you're focused on the main health plan.
The support with policy changes could be handy when someone changes jobs midyear.
Priya N.That happened to us last spring. Knowing what could be changed and when was the confusing part.
No pressure sounds good, but I would still read every exclusion before signing anything.
We agree, pressure-free guidance is no substitute for reading the policy details, especially exclusions, before enrolling.
It's encouraging to see a local advisor explain options without charging for the conversation.
I hope the plan reviews include checking prescriptions. That's where our costs changed.
Craig D.Same here. One prescription moving to a different tier made a big difference for us.
Prescription costs are an important thing to raise during a plan review. It’s worth checking how each option covers your current medications.
Frisco has plenty of new families who could use help figuring out coverage.
Sofia L.Especially families who just moved here and haven't found local doctors yet.
I'm curious how private plans compare with ACA Marketplace plans for a family of four.
The reminder to compare total costs instead of just premiums is worth repeating.
Does she work with small businesses that only have a couple of employees?
Our plan dropped a doctor one year and we didn't notice until January. Check those networks.
Nice to hear Julie will mention a better option even if her agency doesn't sell it.
Health insurance is confusing enough without having to guess what a deductible really costs.
I'd want to know exactly which private plans she can compare before making a decision.
Robert EllisThat's fair. It would help to know which insurers she works with and when you'd need to compare other options.
Glad she helps after enrollment too, because billing questions always seem to come later.
Keeping my kids' doctors matters more to me than saving a few dollars on the premium.
Keeping preferred doctors can be a deciding factor. Comparing provider networks alongside premiums and other costs gives a fuller picture.
The no fee part caught my eye. How does Julie get paid if someone picks a plan?
Dave ThompsonGood question. I'd ask whether insurers pay her a commission and if it varies by plan.
Good to see someone in Frisco helping families sort through all these insurance choices.
The help after enrollment sounds useful. Billing questions can be a headache.
Billing questions can be frustrating. The agency says it helps clients with those questions and policy changes after enrollment, too.
kim_87Billing questions are where I always get stuck. Having someone to ask after signing up would help.
I'd still ask which insurers she's able to compare.
That’s a smart question to ask. Knowing which insurers and plans are included in a comparison helps you understand the options being presented.
Nice to know Julie helps compare plans without a fee.
Maria G.Same here. It would be nice to talk through the options without paying for the conversation.
Thanks for reading! Julie says her guidance comes at no fee and is focused on each client’s needs and budget.